What Exactly Happens When a House is in ‘Escrow’?
shutterstock_110127494You’ve found the perfect home, put in an offer, and the seller accepted. Congrats! But the deal isn’t quite done yet.

There’s this little thing called ‘escrow’, and it involves a bunch of contingencies that need to be met before you get the keys to your new home.

So, what exactly is ‘escrow’, and what’s involved in the process?

Mortgage Financing

After the offer on the home has been mutually accepted by both you and the seller, and all the terms and conditions of the contract have been agreed upon, the escrow process can start. And one of the more pertinent steps during escrow is for you to secure mortgage financing.

If you were pro-active, you would have already gotten a pre-approval letter from your lender before you even started looking for a home. While a pre-approval doesn’t exactly guarantee that you’ll be approved at the time that your offer on a home is accepted, at least it gets the ball rolling and keeps your lender briefed on your home-buying intentions.

After you’ve given the mortgage lender the address of the property that you’ve accepted to purchase, a statement will be prepared that details your loan amount, interest rate, and any other costs involved. Should the lender approve a loan and provide you with written proof, you can remove the financing clause on the contract and continue on with the escrow process.

Property Insurance

Your lender will want to see proof that your home can be insured, and that the insurance process has already begun before a mortgage can be secured. You’ll need to get in touch with an insurance agent and discuss the type and amount of insurance that your specific property will need.

Lender Appraisal

The lender who is providing your mortgage will want to have the property appraised to make sure it’s actually worth what you agreed to pay for it. Lenders want to make sure their financial interests are protected at all times, and aren’t in the business of lending huge sums of money for properties that are worth a lot less than what buyers agree to pay for of them.

If the appraisal comes in at a price that’s lower than your offer price, mortgage financing will likely be declined, unless you can come up with more money to put towards the downpayment, or if the seller agrees to shave a few bucks off the price to match the appraised value.

Home Inspection

A home inspection should always be part of a purchase agreement, with very few exceptions. While the contract is in escrow, a licensed home inspector will check out the integrity of the property’s structure and finishes. Any problems that are identified will be itemized on a report, along with any suggestions on how to rectify them and the cost associated with doing so.

If any issues are identified, you have the option to renegotiate the price in order to cover the costs of making any repairs, or ask that the seller make the repairs prior to you taking possession. Of course, the seller can always decline, at which point you have the option to either go ahead with the sale anyway, or back out as a result of the home inspection not being satisfactory to you.

HOA Document Review

If you’ve purchased a property in a homeowner’s association, then the HOA documents will need to be reviewed by your lawyer. You could do it yourself, but these documents are lengthy and complex, so you’re better off leaving it to an attorney to review on your behalf.

Analyzing these documents will help identify if there are any potential problems with the HOA, such as pending lawsuits, limited reserve funds, problems with the building, and so on. If you’re not satisfied with what the HOA documents reveal, you can back out of the deal before final closing.

HUD-1 Settlement Sheet

As the closing date approaches, a HUD-1 Settlement Sheet will be prepares which lists all the debits and credits for the buyer and seller. For instance, if the seller owes any back taxes on the property, they’ll be considered as a debit to the seller, and listed on the HUD-1 sheet as such.

Final Walk-Through

If you’ve included a contingency in your contract that allows you a final inspection a couple of days before closing, then you have the opportunity to go back and make sure everything is the way it was when you agreed to buy the property.

The Bottom Line

As you can see, there’s a lot that goes on in escrow, which is why it can often take a while to complete before final closing. But don’t get too concerned about the complexities involved, since your real estate agent will be there to oversee the whole process.
Rules of Etiquette You Should Know Before Buying a Home

rulesofetiquetteIf a good deal is what you’re looking for when it comes to buying a house, the last people you want to put off are the sellers.
The truth is, there’s a certain etiquette that buyers should follow throughout the home-buying process, and failure to follow it could actually cost you a lot of money.

At the end of the day, it all comes down to being courteous and having some common sense. Even if you mean no harm, you could inadvertently turn the sellers off with a certain gesture or comment that could potentially sabotage your negotiating power.

Stick to the following rules of home-buying etiquette to make sure the experience is a good one.

Stick With Reasonable Viewing Times

Use common sense when it comes to the days and times that you want to go see a listed home. Generally acceptable viewing times are typically between 10am and 8pm throughout the week. Asking to booking a showing at 10pm on a Tuesday night or 7am on Sunday morning isn’t going to cut it. Agents will likely get shut down if they ask the sellers for a showing at any one of these unreasonable times.

Don’t Demand Last-Minute Appointments

While your agent is working diligently to find you the right home, he or she is not at your beck-and-call. While many times agents and sellers can accommodate an immediate showing, many times they cannot.

While it doesn’t hurt to ask if there’s a last-minute time slot available, don’t demand it. The typical protocol is to book showings at least 24 hours in advance to allow the seller to make arrangements to not be home during the showing, and to have the home adequately prepped to be viewed. It also helps agents ensure that there is free time in their schedules to accommodate an appointment.

Skip the Unauthorized Photography

When you’re at a viewing, don’t whip out your smartphone and start snapping photos of the interior and exterior of the home unless you’ve been given direct permission to do so. That’s just rude and inconsiderate. After all, it’s not a public place – it’s still the sellers’ home, and it’s private property.

Don’t Deal With Any Other Agent if You’ve Already Signed With One

If you’ve already signed a contract with an agent, don’t call the listing agent of a home you’re interested in seeing. Actually, don’t call any other agent at all except your own. Even if your agent is away on holidays, proper etiquette would entail speaking with the agent who is covering for yours while they’re away. Not only is it discourteous to your agent and the other, it could even cost you money considering you’re under contract.

Be Honest With Your Agent About How Serious You Are About Buying

Don’t waste your agent’s time, nor the time of sellers with showings if your immediate intentions are not to buy anytime soon. Agents and sellers are busy enough without entertaining people who are just curious about seeing how other people live.

And even if you are serious about buying, don’t ask your agent to show you 10 houses in one afternoon. Viewing homes takes a lot of time, and taking up your agent’s entire afternoon is expensive for them. Not only that, but seeing too many homes at once will actually cloud your judgment and make it difficult to remember what you saw in which house. Stick to a maximum of only 3 or 4 home listings for each round of showings.

Make Sure You Can Afford the Place

If you’re looking at a home that’s listed for $600,000, but you can only realistically afford one for no more than $300,000, you’re wasting everyone’s time, including your own. Maybe you really do think you can afford the place, and are just naive to the whole home buying process.

That’s where a mortgage pre-approval can come in handy. This will give the lender a chance to analyze your income and current debt to see what you can realistically and comfortably afford. That way, you can focus only on the homes that fit your budget.

Many real estate agents actually require their clients to be pre-approved, and many sellers prefer to see an offer come in from prospective buyers who already have a pre-approval letter from their lender.

Be Polite and On-Time at Showings

This one goes without saying, but it’s still worth mentioning. Be polite to your agent, and to the sellers if they happen to be present. And don’t go sifting through clothes drawers or ransacking the storage closet. Looting around during a showing is definitely not polite.

In addition, make sure you’re on time for the showings. These appointments are usually only for a half hour to an hour, so you want to use each minute to your advantage to get a good sense of the home. Not only that, but it doesn’t show much respect to your agent to make them wait around forever for you to show up. They’ve likely got better things to do. 

Don’t Directly Contact the Homeowner

If a home is listed through an agent, then it’s protocol for any communications to take place between your agent and the seller’s. Under no circumstance is it acceptable to contact the homeowner directly. Not only will you seem overly aggressive, you’ll likely upset the homeowner.

Don’t Act Like the Home is Yours Until it Actually is

Even if you’ve fallen madly in love with a house, and have gone so far as to put an offer on it, the house isn’t yours until the keys are physically in your hands. Don’t show up to the home unannounced and start taking measurements for the sunroom addition you’ve got planned, or where you want the pool to go. Wait until the deal is formally done before you start making any plans.

Don’t Make Comments About the House When the Seller is Around

If the seller happens to be present when you’re viewing the home with your agent, reserve your comments until you’ve left. The homeowner might not appreciate hearing your thoughts on the outdated paint colors or the unattractive living room furniture. You’ll only hurt their feelings, as well as your negotiating power.

The Bottom Line

These tips aren’t hard to follow. In fact, they can be applied to any aspect of life. Use some common sense, be courteous, and be open and honest so that everyone’s happy.

What to Do When You Find Your Dream Home . . . But It’s Not For Sale

dreamhomeforsaleDepending on where you’re looking to buy, there could very well be a major supply shortage.
But don’t let slim pickings in your local housing market stand in the way of you snatching up your dream home. If the listings are limited in your area, consider sending letters to homeowners expressing your interest in buying.

The worst case scenario is that you’ll get a simple “not interested.” But you’ll never know the answer if you don’t ask!

Plenty of buyers across the country are now living comfortably in their homes by taking this leap of faith. But how homeowners are approached is important, which is why you’d be better off having a real estate agent act as a buffer in this interaction.

Many homeowners might find it a bit odd to get an unsolicited offer on their homes. Many might even think it’s nothing but a scam. But if the approach is dignified – and the price is attractive enough – they just might take the bait.

Sure, the odds are stacked against you in this solicitation – only 1 out of 10 homeowners will actually agree to the offer. But that means that the rest – about 10% – actually do agree to sell after a prospective buyer approaches them with an attractive offer.

The point is that there’s still a chance of landing the home simply by asking.

In fact, you may be surprised at how many homeowners have contemplated selling, but simply never got around to it. Sometimes all it takes is making the first move.

In fact, this tactic is not entirely out of the ordinary in markets with sought-after properties, like San Francisco or Seattle. It’s actually pretty common in markets like these where the local market is very active.

Many homeowners of properties that have desirable features won’t completely take the idea of selling off the table. If the right offer comes along, they just might be open enough to taking it.

Name the price, and some homeowners just might accept. 

Of course, if you decide to offer to buy a home that’s not listed for sale, it’s important to keep in mind that it’s the seller who’s in the driver’s seat when it comes to the negotiating table. They can basically name their price.

Obviously, you don’t have to pay it, but you do have the power to choose what price you’ll consider. If you’ve been in the market for a long time and are growing tired of looking, you might not mind paying a slightly higher price.

Just be careful that you don’t pay much more than what the home is really worth according to current market values, or you’ll start running into problems with your lender or with the amount of equity that you’ll be left with in the home.

So how do you go about offering to buy a home that’s not currently for sale?

For starters, have your real estate agent set up alerts on specific property addresses of homes that tickle your fancy, even if they’re not listed for sale at the present moment. If any action happens on these properties, you’ll get an email alerting you.

Foreclosure listings are also an option. And pre-foreclosure listings offer even more possibilities. If a current homeowner is in default on the mortgage, but the bank has yet to take any action, you might have the opportunity to swoop in and take the home off their hands before foreclosure actually finalizes.

Your real estate agent can also pull a report of listings that have expired over the past couple of years or so. Many times these listings simply got stale after not getting any bites. Or perhaps the owners were able to get over some of the perceived negatives about the home and decided to stay put – for the time being, anyway.

Sometimes the owners might still have the thought of selling in the back of their minds. Maybe the situation is more favorable to sell today, compared to what it was back when they first listed their homes.

Whatever the case may be, offering to buy a home that’s not currently listed is a strategy you might want to consider in a market where demand outweighs supply.

Have a friendly note drafted up, and express your admiration for the home, which most sellers will likely appreciate and consider a compliment.

If they’re not ready to sell, perhaps you can come up with an arrangement that will soften the experience and ease into the transition, such as coming up with a rent-to-own agreement at first.

It should be noted that it’s illegal to put anything in another homeowner’s mailbox. So make sure you either leave the letter at their door, or send it via the postal service addressed to the “resident.”

Even if the homeowners don’t seem interested in selling right now, they’ll have your number handy in case they change their mind in the near future.

The lesson here is that when looking for a home to buy, you don’t always have to rely solely on “For Sale” signs. Think outside the box, and you just might wind up with the house of your dreams.

Can Your Neighbor Legally Object to the For Sale Sign on Your Property?

signmainWhen your home is listed for sale, you want it to get as much attention from prospective buyers as possible. Imagine the attention that your home would get if you planted a For Sale sign that was framed in flashing lights and was as big as the house itself.
The thing is, local governments can regulate these signs based on their esthetics, as well as where they are placed. And if you’ve got one of those neighbors who likes to complain about everything, you can bet that your sign will be questioned if it doesn’t fall within these established regulations.

But don’t fret – federal courts have established that the use of signs – including For Sale or Open House signs – is protected by the first amendment to the Constitution. Any local government regulations need to be “content neutral,” which means they can’t flat-out prohibit the use of these signs when you’re trying to market your property’s listing. 

They do, however, have the right to regulate signs based on esthetic and safety purposes. So that bright, flashy sign we mentioned earlier would most definitely fall under the “denied” category.

You can find more specifics about the power that local governments have when it comes to For Sale signs on private property in the California Civil Code (sections 712 & 713) itself. The code states that owners or their real estate agents have the right to put a For Sale sign on the owner’s private property, or on the private property of an individual who provides consent.

Once this right is established, the signs themselves need to meet certain criteria. For starters, the sign needs to be located in a logical spot where the public has clear view of it. The sign also needs to be a fair size with a reasonable design, and not compromise traffic and public safety. Basically, the sign shouldn’t abut the curb and spill onto the roadway. In this case, you can bet the sign will be yanked.

The local government can specifically define these criteria, as long as they are reasonable. Once these restrictions are established, a separate private entity can’t just swoop in and make further demand or limitations.

Case in point: HOAs. If the city has already stated that your sign meets the criteria, the HOA can’t make up a more prohibitive rule. So, if the city’s current sign ordinance states that For Sale signs can be any color, an HOA can’t make up a rule that says signs can only be emerald green.

That should help homeowners breathe a sigh of relief if their HOAs are known to be sticklers.

Unfortunately, there is a potential loophole in the matter of private entities like HOAs infringing their absurd rules about For Sale signs. If the city doesn’t have an established rule about a specific trait, then an HOA can actually legally enforce their sign rule, as silly as it may sound. For instance, if the city’s sign law specifically stated that any color is allowed, the HOA’s demands would have no ground to stand on.

Thankfully, the federal court recognizes the legal right that local governments have when it comes to managing For Sale signs and ensuring that the regulation content is neutral. Hopefully, the city you live in has reasonable sign statutes that are spelled out in detail so you can plant your For Sale sign on your front lawn in peace.

7 Things That Can Drive Your Property Taxes Up

Property taxes are tough to figure out. The federal property tax code alone is thousands of pages long, let alone the local codes all over the country.

In a nutshell, property taxes are determined by a home’s assessed value and the property tax rate for that specific town or county. Sounds simple enough, but then there are all the other dozens of factors that can come into play that can result in higher taxes.

One thing’s for sure: no one likes paying property taxes, or any other kind of taxes for that matter. And homeowners certainly don’t like seeing an increase in these taxes, either. But the amount you’re paying today could increase tomorrow for a variety of reasons.

Here are a few things that can cause your property taxes to go up.

1. Increase in Area Value

Everyone wants to live in a nice area that’s highly valued. After all, the higher the value of the community as a whole, the higher the value of the properties within it (with certain exceptions).

A number of things can cause an area’s value to increase. Maybe the local economy is seeing a boost due to increased employment opportunities. Or perhaps a golf course is being put in nearby your home. Even the construction of new luxury homes nearby can have a big impact on the assessed value of your property.

The opposite is also true. Think about areas with an abundance of hydro towers or chemical plants. How do you think the property tax assessments of homes in these types of communities compare to properties in a golf course community?

propertytaxneighborhood

2. School Funding

Local property taxes are a big source of funding for schools and community colleges. If existing educational institutions in the area are asking for money to make improvements, for instance, the money may often come from property taxes. In that case, you can expect your tax rate to get a boost, thereby increasing how much you pay every year to live where you are.

3. Budget Cuts

Some of the revenue that comes from property taxes are put towards essential services for the area, such as the police and fire departments, libraries, and others. If the state that you reside in decides to slash funding for these services in your area, where is the money going to come from? Why, the local homeowners, of course!

Even when there’s a downturn in the local economy and real estate market, your property taxes are still vulnerable to increases. And one of the biggest culprits for this annoying phenomenon is budget cuts.

4. Increasing Living Space

OK, so there’s not a whole lot that you can do about keeping a cap on property tax rates in your area when it comes to the above factors, but there are things that you as a homeowner might do to inadvertently increase how much you pay in this realm.

In most states in the US, more living space typically translates into a higher property tax rate. If last year your home measured at 1,200 square feet, for example, but that sunroom addition you put in this year brought your home’s size up to 1,800 square feet, you can bet that your property taxes will increase after your home’s been reassessed. 

Whether you convert the garage into a rec room or build a completely new addition to the home, increasing the livable space of your home will increase its value, and therefore its property taxes, too.

5. A Pool, Deck, and Other Outdoor Additions

Not only can an improvement on the actual home itself increase your property taxes, improvements in your outdoor space can do the same. While property tax systems differ from one state to another, as well as among local municipalities, properties will usually be reassessed when improvements are made.

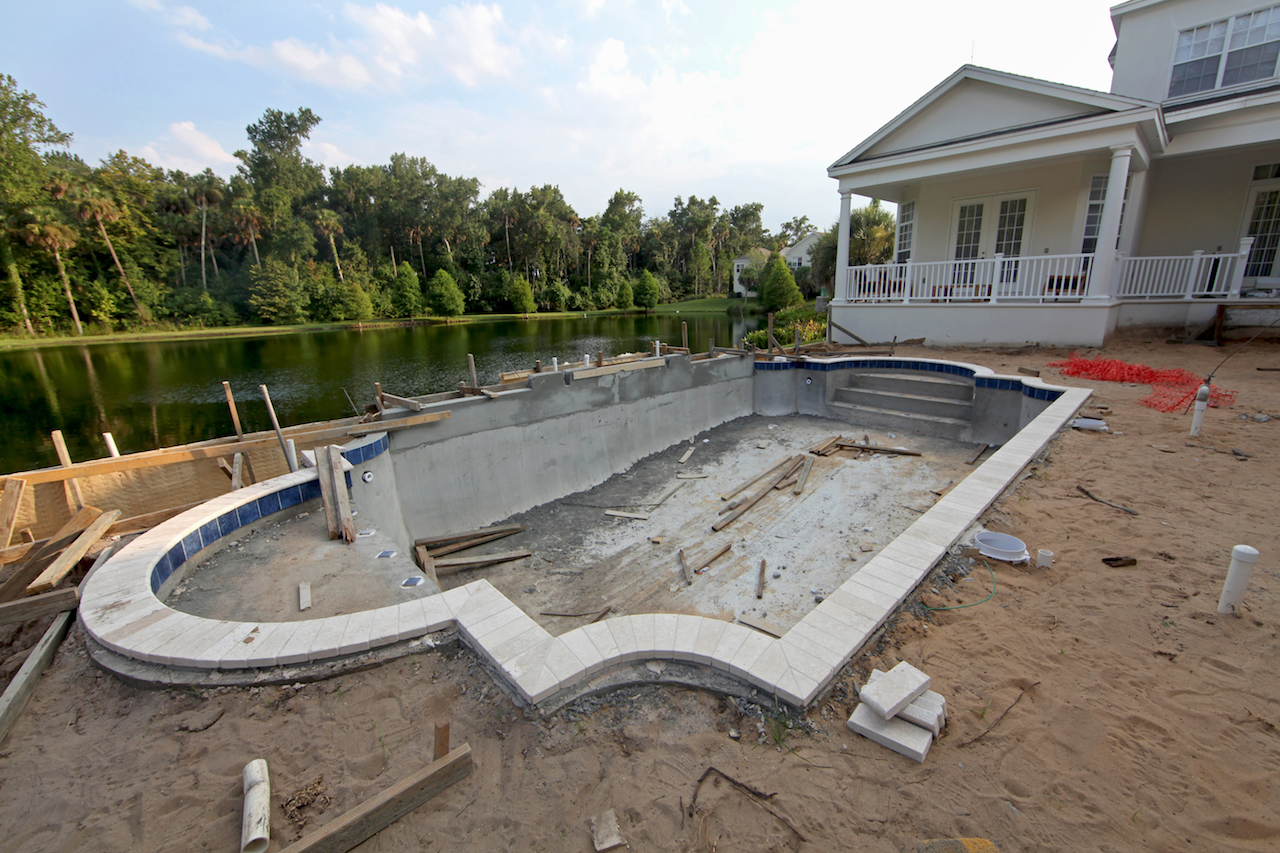
Putting in an in-ground pool or building a big deck both qualify as tax-affected improvements. Your local tax assessment office will calculate the property value using the percentage of market value using comparables of other nearby properties in your area.

The amount that your property value will increase by will depend in your local market. Adding a pool might add 8 percent to a property value in one area, or as much as 30 percent in another.

propertytaxpool

6. Renovated Kitchens

Any professional real estate agent or appraiser will tell you that one of the best ways to increase your property’s value – and therefore its resale price – is by renovating the kitchen. This space is typically considered the hub of a home, and its condition is directly related to the perceived value of the property. 

But along with an increase in property value comes a hike in property taxes. Even if the actual space doesn’t increase in size, the overall condition of the home has been enhanced. And according to Uncle Sam, that warrants an uptick on your tax bill. 

propertytaxkitchen

7. Curb Appeal

Anything that enhances the look of a home’s exterior is fair game when it comes to property tax increases. Even seemingly modest things like a flower patch or vegetable garden can have an impact on the numbers you see on your property tax bill.

While tax assessors need to follow strict guidelines when they evaluate properties, there is still a bit of wiggle room when it comes to subjective opinions. So, if they think your home looks more attractive than next door’s house because you’ve got a few flowers and shrubs versus your neighbor’s barren front yard, your home may be given a higher assessed value.

The next time you take a gander at your property tax bill and notice that it’s higher than the last one, consider if any of the above factors came into play and had a hand in the price increase.

Top 7 Tips to Find the Right Investment Condo

If you’re the “buy and hold” versus the “fix and flip” type when it comes to condo real estate investment, there are a certain set of factors that warrant some serious consideration. The most successful real estate investors are those who’ve put a lot of time and thought into an effective long-term real estate investing strategy from the get-go.

Whether you’re a newbie to condo real estate investment, or need to improve on your existing strategy, the following tips can help you sharpen your skills and increase the odds of being successful.

1. Decide on Either Pre-Construction or Resale

There are obvious pros and cons to both, and it’s up to you to weigh them according to your finances and your goals. When you buy a unit in a new condo building that’s still in the pre-construction phase, you’re likely to pay a lower price compared to a resale unit because of the price appreciation over time. You’ll also be able to have your input in the layout of the unit and the fixtures that are installed.

But buying pre-construction also means you’ll be sitting on the sidelines waiting for the building and your unit to be finished, which means a delay in raking in the profits from your investment. In the meantime, your deposit is sitting there when it could have been working for you elsewhere. 

On the other hand, a resale will almost certainly come with a higher listing price compared to pre-construction. However, you can typically get your hands the unit a lot sooner, and won’t have to put up with construction delays that are  common in new developments.

2. Make Sure the Condo Has a Decent View

It might be worth it to pay the premium for a view that renters – and buyers – would be thoroughly impressed with. If there are other units in the same building that are being offered for rent, you want to have the unit that stands out.

A unit that overlooks a cityscape, park, ravine, or any other attractive feature will likely get more interest and demand a higher rental price compared to a unit that’s overlooking the garbage dumpster and parking lot. And when it comes time to sell in the future, you’ll be able to ask for a higher selling price too.

investmentcondoview

3. Look For Condos With Sought-After Amenities

What do people in the area that you’re looking in expect to have at their disposal in a condo building? If the general consensus is that a swimming pool and fitness center are must-haves, for instance, then make sure the building you’re buying into offer those amenities.

It could very well be that a prospective renter is comparing your unit to the one across the street. If the other building has a pool and yours doesn’t, you could be losing out. Of course, it’s important to note that along with all these added frills comes a higher HOA fee. Make sure you account for this fact when crunching the numbers to see what type of income you can generate from your investment.

4. Buy Into a Good Location, and Learn Everything About it

Real estate is all about location. It’s the age-old mantra of the industry, and it plays a key role in property values. Ideally, you want to look for a property that’s close to public transit and local roadways, and offers quick and easy access to city centers.

Check the building’s walking score to see how easy and fast it is for residents to stroll over to shops, restaurants, parks, and so forth. Zero in on a few areas that offer these features, and learn everything there is to know about them. The more of an expert you become on an area, the more knowledgeable you’ll get when it comes to local property values. This type of info is invaluable to a real estate investor.

investmentcondolocation

5. Consider the Maintenance Fees

Look into the average HOA fees in certain areas. Pick an area or two, and compare the fees from one building to the next to see if they’re on par. If the fees in one particular complex are too high or low, these are potential red flags that prompt further investigation.   

High fees might eat into your profits. And while low fees are definitely appealing, dig deeper to find out why they’re so cheap. Many times new condo buildings offer low fees during the first year or two after registration, but then jack them up in subsequent years to cover added expenses. Make sure you take a magnifying glass to the fine print.

6. Understand the HOA Rules

Condos are governed by HOAs, which means there will definitely be a rule book that owners and residents need to strictly follow. Aside from not allowing gas barbecues on the balconies or having rules about the maximum size pet dogs can be, many HOAs have rules about renting units.

HOAs have the legal right to restrict rentals, within certain boundaries. If these restrictions will affect your particular rental unit, you could wind up losing money instead of making it.

7. Work With a Real Estate Agent Experienced in Your Local Condo Market

Your best ally when it comes to finding the ideal investment condo is a real estate agent. Working with a professional who is well-versed in investment properties in specific areas, and understands the condo market inside and out will be able to provide you with invaluable insights into which properties are duds, and which ones are potential gold mines.

At the end of the day, your real estate agent can help you spot a good investment and avoid a bad one in order for you to maximize your profits and protect your capital.

How Does the Stock Market Influence Mortgage Rates?

You lock into a fixed-rate mortgage at 5.5% when you first buy your home, and by the time you’re up for renewal, the mortgage rate is down to 3%.

While you’re not exactly disappointed that you’re now offered a lower interest rate – which equates to a lot of money saved in interest payments over the life of your mortgage – you can’t help but wonder why mortgage rates are prone to such wild fluctuations.

We’ve been in an extremely low mortgage rate environment over the past few years, which has made buying a home somewhat more affordable. But anyone – Baby Boomers in particular – who purchased a property back in the early 1980’s surely remembers when rates were ridiculously high – as high as 18.45%, to be exact.

Imagine paying for a home with that monster of a rate attached to the mortgage? It’s easy to understand how many homeowners ended up losing their homes simply because they were upside down in their equity.

The reasons for mortgage rates moving up and down like a roller coaster are wide in range, but the stock market is certainly a big player in the game.

stockmarkethouse

Mortgage-Backed Bonds’ Influence on Mortgage Rates

While there are a few factors that contribute to which direction mortgage rates run in – namely inflation – the stock market is a key influencer.

But it’s helpful to take a step back to really get the gist of how mortgage rates are essentially determined. Mortgage-backed bonds (MBS) are at the root of changes in mortgage rates. Fannie Mae and Freddie Mac issue these MBS’s, which are backed by the interest that’s paid out by mortgage holders. Similar to the stock market, MBS’s are traded on an exchange.

An inverse relationship exists between mortgage rates and the price of MBS’s; when MBS prices go up, mortgage rates do down. The reverse is also true. 

Essentially, when there’s an increase in economic fear, there tends to be a mass exodus of investors from the stock market. Instead, these investors hedge their funds in safer Treasury bonds. With demand spiking for these bonds, yields drop – there’s simply no need to keep them up to attract investors. 

Conversely, a rally in the stock market encourages investors to sell these bonds in favor of purchasing stocks.

All this is based on the notion that both the stock and bond markets are vying for the same investment money. In other words, investor will choose to either invest money in the stock market or the bond market.

As a general rule of thumb, investors choose stocks over bonds when a greater return over time is sought, but stocks are also associated with heightened volatility. On the other hand, the returns on bonds are usually a lot lower compared to stocks, but they’re generally less volatile.

For this reason, investors typically turn to bonds to hedge their funds when the overall market and economy is unstable. 

If the stock market is down, it means investors are liquidating their stocks and buying into bonds. When this happens, bond prices soar, while mortgage rates plummet. And when the stock market is bullish, investors are likely selling their bonds and switching over to a more stock-heavy investment portfolio.

In this environment, mortgage rates rise as bond prices tumble following a surge in supply.

Of course, there are a host of other factors that influence how mortgage rates behave from one day to the next. But the stock market certainly has it’s role in the whole process.

Nevertheless, rates are incredibly low these days, and have been hovering around historical lows for years. It will be interesting to see how fast and far they climb in the near future given the current economic turmoil across global markets.

5 of the Worst Mortgage Refinancing Mistakes to Avoid

Want to take advantage of a lower mortgage rate? Looking to switch from an adjustable- to a fixed-rate loan? Need to tap into the equity in your home to cover a large purchase? Any one of these are good reasons to consider refinancing your mortgage.

But while a refinance may be just what you need to do to save some cash, how you go about it makes all the difference. Make sure you avoid the following refinancing mistakes before committing yourself to one.

refinancemistakesmain

1. Assuming Your Home is Worth More Than it Actually is

There are a bunch of reasons why you might want to consider refinancing your mortgage, and one of them is to tap into the equity that you’ve built up in your home. Whether you need to pay for your kid’s exorbitant college tuition fees, or are planning on taking a long-awaited trip around the world, you’re going to need a good chunk of change, which you can siphon from the equity in your home.

Much of your home equity depends on what the current market value of your property is. Do you really know what your home is actually worth? Just because it may have been appraised at $250,000 a couple of years ago, for instance, doesn’t necessarily mean it’s worth that much now. Real estate markets fluctuate, even though they tend to increase over the long haul.

Have you even had your home appraised at all? It would be a crying shame to refinance your mortgage assuming that your home is worth more than it really is, only to wind up with a refinance offer that’s higher than you expected simply because there’s not enough equity in your home.

2. Making Huge Purchases on Credit Right After Applying For a Refinance

Fiddling around with your credit score when applying for a refinance is a bad idea. When it comes to refinancing, you want to make sure that the rate you wind up with is the one you anticipated from the get-go. Don’t go out and buy a new vehicle or take out a student loan right in the midst of your application.

Piling on the debt is the last thing you want to do, as it will do nothing but negatively affect your credit. Your lender just might decide to slap you with a higher rate, or deny your refinance altogether if you’re deemed to have too much debt on the books.

3. Not Shortening Your Mortgage Term

While it’s nice to have a lower monthly payment, your ultimate goal is to pay your house off in full in as short a time period as possible. Doing so will allow you to cut back on the total amount that you’ll have to pay towards interest. When you refinance your mortgage, you’d be making a huge mistake if you don’t consider shortening the length of your loan.

Let’s say your current mortgage has a 30-year amortization period, and you’ve been paying it for three years now. If you refinance to another 30-year mortgage, you’re basically putting yourself in a position to pay your home off in 33 years, considering the three years you’ve already been paying. Not only that, but you’ll probably be paying more in interest that you would have had you not refinanced at all.

4. Not Knowing That You Can Annul the Mortgage Deal

If you’re in the market to refinance your mortgage these days, you’re in luck. With the new Truth In Lending Act (TILA) that came out just last year, borrowers have a lot more rights when it comes to the information they’re privy to. In addition to providing heightened transparency with mortgage documents, the Act allows borrowers to nullify a mortgage refinance deal under specific circumstances within three days of closing.

If you have second thoughts about the refinancing deal, you can back out, as long as it’s not with your current mortgage firm. Of course, you should take your time doing your due diligence before signing on the dotted line rather than resorting to rescinding the refinance. But if worse comes to worse, you should know that annulling the deal is an option if absolutely necessary.

5. Not Comparing Quotes From Different Lenders

Perhaps the biggest blunder you can make with a mortgage refinance is failing to shop around to see what various lenders are offering in terms of refinancing rates. Even a fraction of a percentage point can mean thousands of dollars saved over the life of the mortgage. You can think of a lot of better ways to spend that cash other than on interest payments.

Not only does shopping around allow you to find the lowest interest rate, it’ll also give you the opportunity to land ideal terms and conditions for your loan that best suit your financial situation. This applies both with a refinancing and a conventional mortgage.

The Bottom Line

Just like with any issue surrounding your finances, it’s always best to do your homework and find out as much as you can before putting yourself in a position that you can’t get out of. Refinancing is about making the most of your equity and money, so make sure your decision improves your financial situation at the end of the day.

Can You Gift Money for a Down Payment? Yes! And Here’s How

These days, it can be pretty tough to scrape together a good chunk of change to use as a down payment for a home. The financial recession, housing crisis, and weak job market hit a lot of Americans hard.

And the millennial generation of today is taking their time moving out of their parents’ homes specifically because they simply cannot come up with enough money to warrant a half-decent down payment.

In fact, more parents are helping out their adult children purchase a home these days compared to decades past; 17 percent, to be exact, according to a recent survey.

Depending on the exact type of property being purchased, its location, the lender, and the type of mortgage, the down payment on its own can be a huge sum. In order to help cover this expense, many buyers turn to family and friends to chip in. And while that’s helpful and all, there are actually certain rules that apply to this type of gifting before the funds can be used to put towards a home purchase.

The Money’s Got to Come From Family

While you might be generous enough to want to financially help out your co-worker’s niece or your best friend’s son to buy a home, your money won’t be good in these circumstances. You can gift down payment funds to your kids, grandkids, and even your siblings, but not to your neighbor, friend, or fourth cousin on your mother’s side.

Not only does it matter who is giving the money, it’s also necessary for the cash to be easily tracked. Lenders want to have total transparency when it comes to where the funds are coming from, and are cautious when it comes to all-cash gifts that are put towards a mortgage. If you’re going to give money as a gift for a down payment, do it through a wire transfer or check instead of cold-hard cash.

Avoiding ‘Gift Taxes’

Seems that Uncle Sam is always lurking when it comes to money, and that’s no exception in the case of gifted funds for down payments. In order to avoid paying taxes on your monetary gift, you need to stick to a cap of $14,000 per individual. However, you and your spouse could give up to $28,000 to one child, which implies two separate gifts. That number can be doubled if you and your spouse are gifting your child if he or she is married. Just make sure that each check is no more than $14,000 a-piece, or you’ll be dinged by the IRS.

Down Payment Borrower Contribution

The rules when it comes to borrower contribution as opposed to a gift will vary depending on the exact type of mortgage. For an average conventional mortgage, all of a 20 percent-or-more down payment can be in the form of a gift. If less than 20 percent is being put down, part of it needs to come from the individual receiving your monetary gift; this amount will vary by loan type.

Fannie Mae requires a 3 to 5 percent contribution from the borrower, and Freddie Mac requires a 5 percent minimum borrower contribution if the down payment is under 20 percent.

In addition, the transaction needs to involve a two- to four-unit property that’s either a primary or secondary home. VA and FHA mortgages will only allow monetary gifts to be used towards primary homes.

Down Payment Gifts Need to Be Well-Documented

The money that you give as a down payment contribution needs to be documented. Usually, mortgage lenders will provide a letter for both you and the individual you’re gifting to sign, which shows that the money was actually a gift and not a loan that will need to be paid back.

Lenders will typically ask for bank statements from those who are planning to use a monetary gift towards their purchase in order to comply with the Patriot Act. They want to know that the funds aren’t going to be used for any nefarious reasons, like money laundering or funding for any terrorist activity.

The rules will vary from one lender to the next, so you’d be well-advised to find out exactly what your beneficiary’s specific lender requires from the both of you.

The Bottom Line

The gift-giving season may have just passed, but the spirit of generosity doesn’t have to. If your loved one is having a tough time coming up with the necessary funds to put towards a down payment, helping them out is a noble gesture. Just make sure you’re aware of the rules that come along with offering gift money for a down payment to avoid headaches and pesky tax implications.